
How to Finance a Fabric Building for Your Farm
You’ve found the right fabric building for your farm. Now comes the next question: how will you pay for it? In fact, fabric building financing gives you more than one path. Specifically, you can pay cash, use a line of credit, or lease to own, and public loan programs in Canada and the United States add even more options.
Here’s how each option works, and what to weigh before you choose.
| Option | You own the building | Upfront cost | Payments |
|---|---|---|---|
| Cash | Right away | Full price | None |
| Line of credit | Right away | Draws on your credit | Set by your lender |
| Lease to own | When the lease ends | Typically no large down payment | Monthly, semi-annual, or annual |
| Public loan programs | Right away | Varies by program | Set by the program |
Buying With Cash or a Line of Credit
First, paying cash has a clear advantage: you own your building immediately, and you don’t have to manage an ongoing payment plan. However, running a farm already costs a lot. Between land taxes, equipment and machinery, repairs and maintenance, and feed and livestock, the bills add up fast.
Because of that, a large cash purchase can tie up your cash reserves or your lines of credit. As a result, you may have less room for the other expenses your operation depends on.
Beyond that, paying cash can mean waiting. For many farmers, saving the full amount upfront delays the building they need to grow their operation.
Lease to Own: Keep Your Cash Working
In contrast, leasing leaves your cash reserves and lines of credit untouched. Instead of one large payment, you spread the building’s cost over years with monthly, semi-annual, or annual payments. Lease-to-own also typically works without a large upfront down payment.
Best of all, you own the building once the lease is complete, no matter how short or long your lease is. That means construction can start sooner than you think.
To compare both paths in more detail, read our guide to leasing vs. buying a fabric building.
Payment Schedules That Follow Your Seasons
You don’t grow crops year-round, so why make payments year-round when cash flow is tight? Instead, with leasing, you can customize your payment schedule to fit your operation. For example, you can line up payments with the times of year when your farm brings in income.
Tax Considerations
Taxes can also shape your decision. When you buy a fabric building with cash, it generally depreciates at a slower rate than your other farm equipment. So you’ll claim those deductions over decades.
On the other hand, with leasing, you can potentially claim your building’s deductions sooner. For example, leasing may allow you to deduct your lease payments over the term of the lease. Tax rules vary by country and situation, so always speak with your accountant before you buy or lease any building.
Fabric Building Financing in Canada
In Canada, Britespan works with Catalyst Finance Company for agricultural customers across the country, except Quebec. Our lending partners offer fast and flexible financing and leasing programs, and customized payment schedules are available.
In addition, Canadian farmers can explore Farm Credit Canada’s land and building financing. FCC lets borrowers “schedule payments around growing cycles, off-farm income and during construction.” It also lists options such as deferred payments and interest-only payments.
Fabric Building Financing in the United States
In the United States, the USDA Farm Service Agency (FSA) offers loan programs, including two that can apply to farm buildings.
Farm Storage Facility Loans
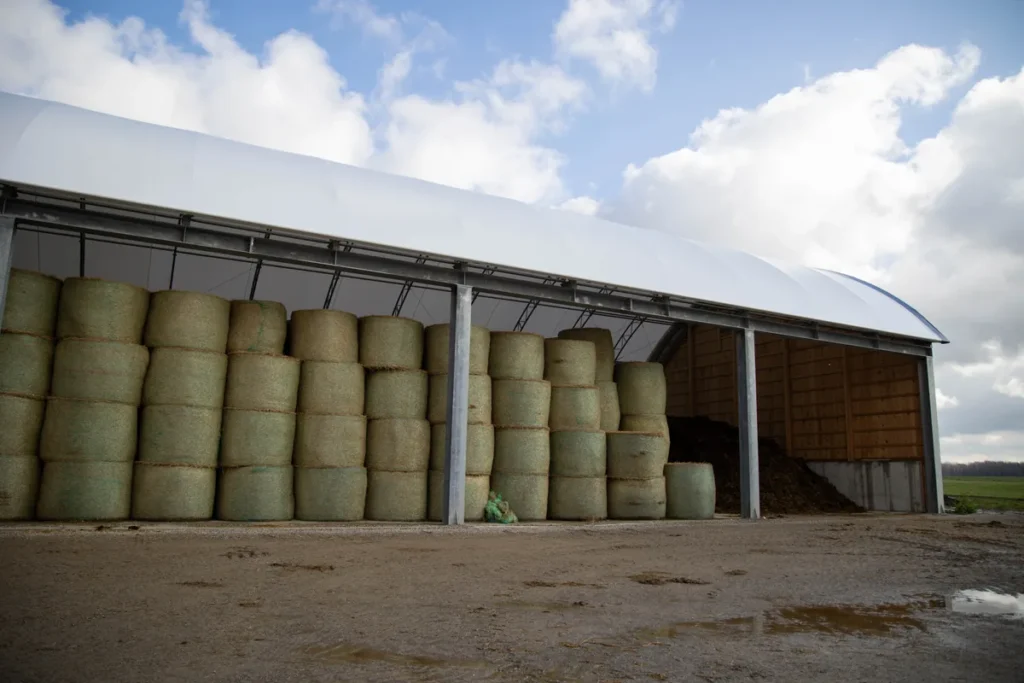
The Farm Storage Facility Loan program lists hay barns among its eligible facility types, and it covers both permanent and portable storage. Specifically, eligible commodities include grains, oil seeds, and hay. Loan terms range from 3 to 12 years.
Farm Ownership Loans
FSA Farm Ownership Loans can cover the construction of farm buildings and improvements to existing structures.
Eligibility depends on your operation and your project, so check with your local FSA office before you plan around either program.
What Will You Finance?
Financing opens the door to the building your operation needs now. Maybe it’s a new barn to improve the health and productivity of your livestock. Perhaps it’s a storage building to protect your equipment and machinery, or a hay barn to maintain the quality of your crop. Whatever you’re planning, the right financing means you don’t have to wait years to build it.
Common Questions About Fabric Building Financing
Can you finance a fabric building?
Yes. You can pay with cash or a line of credit, lease to own, or apply through lenders and public programs. Britespan works with lending partners, and you can find details on our financing page.
Is it better to lease or buy a farm building?
It depends on your cash flow and your plans. Buying gives you ownership right away. Meanwhile, leasing keeps your cash and credit free and spreads the cost over time, and you own the building at the end. Your accountant can help you compare the tax impact.
Do I need a down payment to lease a fabric building?
Lease-to-own typically works without a large upfront down payment. Your lender confirms the terms for your situation.
Can I use an FSA Farm Storage Facility Loan for a hay barn?
The program lists hay barns as an eligible facility type. However, approval depends on your project, so confirm with your local FSA office first.
Talk to an Expert
The right financing can move your building project forward sooner. To learn more about fabric building financing, speak with your local Britespan Authorized Dealer, visit our financing page, or contact one of our lending partners.
*Always consult with your accountant regarding taxes before acquiring any equipment or buildings.
Updated: November 2, 2026
Written by: Lindsay Kenny | Technical Review by: George Lawless